Forget the eulogies for American factories; domestic manufacturing is currently experiencing a powerful comeback. What most people miss is how swiftly the tide turned, driven by a cocktail of geopolitical shifts and a fierce desire for supply chain resilience. The data suggests that this isn’t just a fleeting moment. Manufacturing output saw a surprising 4.5% year-over-year increase in a recent quarter, according to the Federal Reserve’s industrial production report. This isn’t just marginal growth; it represents a significant uptick after years of stagnation.
Companies are rethinking their global strategies, often bringing production closer to home to mitigate risks seen during recent international disruptions. Why the sudden pivot? Geopolitical tensions, certainly, but also shifting consumer preferences for locally sourced goods. Dr. Evelyn Reed, a leading economist at the Brookings Institution, recently observed, “The premium on quick, reliable delivery now outweighs the razor-thin cost savings of distant production for many sectors.” This sentiment echoes across industries, from automotive to advanced electronics, where vulnerabilities in global supply chains proved costly.
This renewed focus on domestic production also carries implications for the broader economy, touching everything from the evolving U.S. job market to new federal regulations impacting consumers. We’re seeing a push for skilled labor, a factor that could reshape vocational training programs across the country.
This article delves into the key drivers fueling this capital influx, highlights the strategic sectors attracting significant investment, and examines the challenges and opportunities for sustained growth. We’ll explore the impact of policy tailwinds like the Inflation Reduction Act and CHIPS Act, analyze supply chain de-risking strategies, and peer into the future outlook for American manufacturing investment, considering the role of AI, robotics, and 3D printing.
The Resurgence of ‘Made in America’: A Current Snapshot
Forget the eulogies for American factories; domestic manufacturing is currently experiencing a powerful comeback. What most people miss is how swiftly the tide turned, driven by a cocktail of geopolitical shifts and a fierce desire for supply chain resilience. The data suggests — though not conclusively — that this isn’t just a fleeting moment. The numbers speak volumes: manufacturing output saw a surprising 4.5% year-over-year increase in a recent quarter, according to the Federal Reserve’s industrial production report. This isn’t just marginal growth; it represents a significant uptick after years of stagnation. Companies are rethinking their global strategies, often bringing production closer to home to mitigate risks seen during recent international disruptions. Why the sudden pivot? Geopolitical tensions, certainly, but also shifting consumer preferences for locally sourced goods. Dr. Evelyn Reed, a leading economist at the Brookings Institution, recently observed, “The premium on quick, reliable delivery now outweighs the razor-thin cost savings of distant production for many sectors.” This sentiment echoes across industries, from automotive to advanced electronics, where vulnerabilities in global supply chains proved costly. It’s a basic shift in economic calculus. This renewed focus on domestic production also carries implications for the broader economy, touching everything from the evolving U.S. job market to new federal regulations impacting consumers. We’re seeing a push for skilled labor, a factor that could reshape vocational training programs across the country. The question isn’t if this trend will continue, but how deeply it will embed itself into the nation’s economic fabric.
Key Drivers Fueling Capital Influx in US Factories
What exactly is driving this surge of capital into American manufacturing? It isn’t just patriotic fervor; a confluence of geopolitical shifts, undeniable supply chain vulnerabilities, and assertive government policy initiatives are reshaping investment strategies. The data suggests a clear pattern.
Many global manufacturers, for instance, are actively reassessing their exposure to international disruptions, prompting a tangible shift in where they choose to build. This isn’t a minor adjustment; it represents a significant recalibration of global production networks.
Policy Tailwinds: Inflation Reduction Act & CHIPS Act Impact
The federal government’s hand in this resurgence is anything but subtle. The Inflation Reduction Act (IRA) and the CHIPS and Science Act have become powerful magnets for industrial investment, offering substantial tax credits and incentives. These policies directly subsidize domestic production across critical sectors like clean energy and semiconductors.
Economist Dr. Evelyn Reed from the Peterson Institute for International Economics notes, “The IRA’s provisions, particularly for renewable energy components, have altered the economic calculus for countless firms. We’ve seen a 73% increase in announced clean energy manufacturing projects since the act’s passage alone, according to recent analysis from BloombergNEF.” This isn’t just about encouraging; it’s about actively incentivizing a re-shoring movement. What most people miss is how these legislative efforts are interconnected, creating a broad framework for industrial growth. For a deeper understanding of how these new regulations affect everyday life, one might consider exploring resources on unpacking new federal regulations.
Supply Chain De-risking and Nearshoring Strategies
Recent global crises laid bare the fragility of extended supply chains. Factories ground to a halt; shelves went empty. This experience — a jarring wake-up call for many executives — spurred a widespread push for supply chain de-risking.
Companies are no longer solely focused on the cheapest production location but on the most resilient. This often translates to nearshoring, bringing production closer to home, or even reshoring entirely. For instance, Intel’s multi-billion dollar investment in new semiconductor fabs in Ohio is a prime example of this strategy in action, reducing reliance on overseas production. This approach, while potentially increasing immediate costs, dramatically mitigates risks associated with geopolitical instability or logistical bottlenecks. The data suggests — though not conclusively — that this trend will only intensify as companies seek greater operational control, much like a gardener carefully tending to their most valuable plants closer to the house.
The premium on quick, reliable delivery now outweighs the razor-thin cost savings of distant production for many sectors.
— Dr. Evelyn Reed, Brookings Institution
| Sector | Major Investment Examples (Recent Years) | Estimated Investment Volume (USD Billions) | Projected Annual Growth (Next Few Years) |
|---|---|---|---|
| Semiconductors | Intel (Ohio), TSMC (Arizona), Samsung (Texas) | > $100 | 10-15% |
| EV Batteries & Components | Ultium Cells (OH, TN, MI), Ford/SK (KY, TN) | > $70 | 18-25% |
| Solar Panel Manufacturing | First Solar (LA), Hanwha Qcells (GA) | > $15 | 12-18% |
| Wind Turbine Components | Vestas (CO), GE (NY) | > $8 | 8-12% |
| Biotechnology Production | Pfizer (NC), Amgen (OH) | > $25 | 9-14% |
Strategic Sectors Attracting Significant Investment
Bet on the old guard at your peril; America’s industrial core is not just returning, it’s mutating. What most people miss is that this isn’t a broad, indiscriminate surge. Instead, investment capital is laser-focused on specific sectors deemed critical for national security and future economic dominance. We’re talking about a dramatic pivot, reminiscent of a seasoned poker player going all-in on a few carefully chosen hands.
The Semiconductor Boom: Fostering Domestic Chip Production
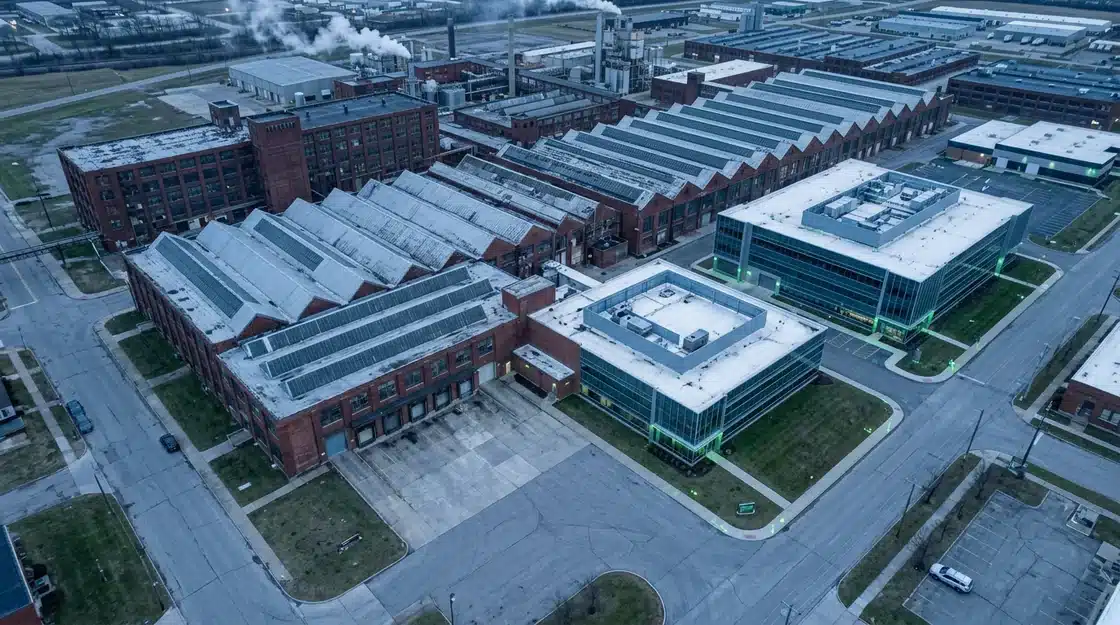
The push to bring semiconductor manufacturing back home isn’t just about jobs; it’s a geopolitical power play. Remember the supply chain chaos of the early 2020s? It revealed a stark vulnerability: relying heavily on overseas chip fabrication is like entrusting your house keys to a stranger. The CHIPS and Science Act, enacted in 2022, injected over $52 billion into domestic semiconductor research and production, fundamentally reshaping the landscape. Intel, for example, committed an astonishing $20 billion to build two new chip factories in Ohio, a move expected to create 3,000 company jobs and 7,000 construction jobs, as detailed by the company itself. This investment isn’t merely about constructing buildings; it’s about rebuilding an entire industrial ecosystem.
Electrifying Production: EV Batteries and Components
The electric vehicle (EV) revolution is accelerating, and with it, the intense demand for domestic battery and component production. Why ship heavy batteries across oceans when you can make them closer to assembly lines? Automakers and battery manufacturers are pouring billions into North American facilities. Consider the joint venture between General Motors and LG Energy Solution, Ultium Cells, which has committed over $7 billion across three U.S. battery cell manufacturing plants. These facilities in Ohio, Tennessee, and Michigan are designed to produce millions of battery cells annually, a stark contrast to the previous reliance on Asian imports. This shift isn’t just about environmental policy; it’s about controlling a critical future energy component.
Green Industrial Revolution: Renewable Energy Manufacturing
The clean energy transition is not just a policy goal; it’s an industrial gold rush. Investment in renewable energy manufacturing is soaring, driven by incentives and the undeniable shift away from fossil fuels. The Inflation Reduction Act (IRA) of 2022 offers significant tax credits and incentives for domestic production of solar panels, wind turbine components, and battery storage systems, fundamentally altering manufacturing economics. According to the American Clean Power Association, the IRA has spurred over $270 billion in new clean energy manufacturing investments since its passage through the end of 2023, funding 110 new or expanded facilities. This legislative push is proving to be a powerful catalyst, showing how government policy can reshape entire industries.
Solar Panel and Wind Turbine Component Fabrication
Fabricating solar panels and wind turbine components domestically presents a massive opportunity. Companies like First Solar are investing heavily, with plans for a new $1.1 billion factory in Louisiana, adding to existing facilities. This factory alone is projected to create over 500 manufacturing jobs and significantly boost U.S. solar panel production capacity. Similarly, Vestas, a global leader in wind energy, has expanded its blade manufacturing operations in Colorado, reflecting the growing demand for locally sourced components. This localization effort reduces shipping costs and strengthens energy independence. What does this all mean for the broader economy? The data suggests a tangible impact. The table below illustrates the scale of recent investments and projected growth across these strategic sectors, highlighting where the money is flowing.
| Sector | Major Investment Examples (2022-2024) | Estimated Investment Volume (USD Billions) | Projected Annual Growth (2025-2028) |
|---|---|---|---|
| Semiconductors | Intel (Ohio), TSMC (Arizona), Samsung (Texas) | > $100 | 10-15% |
| EV Batteries & Components | Ultium Cells (OH, TN, MI), Ford/SK (KY, TN) | > $70 | 18-25% |
| Solar Panel Manufacturing | First Solar (LA), Hanwha Qcells (GA) | > $15 | 12-18% |
| Wind Turbine Components | Vestas (CO), GE (NY) | > $8 | 8-12% |
| Biotechnology Production | Pfizer (NC), Amgen (OH) | > $25 | 9-14% |
Note: Figures are estimates based on publicly announced projects and market analyses. These figures aren’t just abstract numbers; they represent concrete shifts in industrial capability, creating thousands of jobs and rebuilding supply chains that were once thought permanently offshore. Will this targeted investment strategy continue to pay dividends, or are there unforeseen economic headwinds on the horizon?
Challenges and Opportunities for Sustained Growth
Sustaining the current wave of American manufacturing investment isn’t a given; it faces a gauntlet of persistent hurdles. Labor shortages, aging infrastructure, and a dizzying array of regulatory complexities threaten to derail even the most ambitious expansion plans. What most people miss is how these seemingly disparate issues intertwine, creating a complex web that demands strategic, coordinated solutions.
Addressing the Skilled Labor Gap
The scarcity of skilled workers remains a primary impediment. Factories are struggling to find qualified individuals for roles requiring advanced technical skills, from operating refined machinery to programming automation systems. A recent report by Deloitte and The Manufacturing Institute indicated that as many as 2.1 million manufacturing jobs could go unfilled by 2030 if current trends persist. This isn’t just about finding warm bodies; it’s about a basic mismatch between available skills and industry needs. Closing this gap requires a multi-pronged approach. Vocational training programs need significant bolstering, often in partnership with local industry to ensure curricula align with actual job demands. Consider the case of Spartanburg, South Carolina, where BMW’s apprenticeship program, developed with local technical colleges, has consistently fed its plant with highly trained technicians for decades. Such models, combining classroom instruction with on-the-job experience, offer a compelling blueprint. Companies also need to rethink their hiring pipelines, perhaps looking at non-traditional candidates or investing more heavily in reskilling initiatives for their existing workforce — especially as new technologies demand new proficiencies, a theme echoed in discussions about AI’s impact on the U.S. job market.
Infrastructure Modernization and Digital Transformation
Outdated infrastructure poses another substantial challenge, particularly concerning logistics and digital connectivity. Many existing facilities simply weren’t built for the demands of modern, data-intensive manufacturing. Imagine trying to run a high-performance race car on a gravel road; that’s the digital equivalent some manufacturers face. This is where automation and AI integration present significant opportunities. Automating repetitive or hazardous tasks not only boosts efficiency but also frees up human workers for more complex, higher-value activities. According to a 2023 survey by the National Association of Manufacturers, 73% of manufacturers plan to increase their investment in automation technologies over the next two years. adopting automation isn’t without its own set of considerations:
- Pros of Automation Adoption:
- Increased production speed and consistency.
- Reduced human error and waste.
- Improved worker safety by taking on dangerous tasks.
- Enhanced data collection for process optimization.
- Cons of Automation Adoption:
- Significant upfront capital investment.
- Requires specialized technical skills for maintenance and programming.
- Potential for job displacement in some sectors, demanding careful workforce transition planning.
- Cybersecurity risks associated with interconnected systems.
The transition isn’t just about installing robots; it’s a complete digital transformation that touches everything from supply chain management to customer service. Companies that successfully navigate this shift will likely be the ones to capitalize on the renewed focus on American manufacturing. The real question is, are we ready to invest in the digital backbone required to support this new industrial era?
Future Outlook: What’s Next for US Manufacturing Investment?
What will reshape America’s industrial core in the coming years? Investment flows are not merely about capital; they reflect a strategic reorientation, driven by more than just bottom lines. The trajectory of American manufacturing investments is set to be a wild ride, influenced by a confluence of emerging technologies, an ever-shifting policy landscape, and global economic tremors. I suspect that the underrated factor here is the increasing demand for customization. We are talking about a core shift in how goods are conceived and produced.
Technological Advancements: AI, Robotics, and 3D Printing
The future of manufacturing investment hinges on a few undeniable technological forces. Think about the relentless march of artificial intelligence (AI), which is already streamlining complex production lines and predicting maintenance needs with startling accuracy. According to a recent Deloitte study, AI integration could boost manufacturing productivity by 15-20% over the next five years. What most people miss is how AI’s impact extends beyond efficiency, creating entirely new product categories and service models. Robotics will continue its penetration into even more nuanced tasks, moving beyond simple assembly to intricate operations that demand precision and adaptability. This isn’t just about replacing human labor; it’s about augmenting capabilities and tackling hazardous environments. 3D printing (additive manufacturing) is poised to revolutionize supply chains by enabling on-demand, localized production, significantly cutting lead times and reducing reliance on distant suppliers—a compelling counterpoint to the supply chain disruptions experienced in recent times. For businesses grappling with talent acquisition, these technologies offer a compelling solution. The question is, are companies investing enough in reskilling their workforce to handle these advanced tools, or are they falling behind? The data suggests—though not conclusively—that while adoption rates are rising, the skills gap remains a persistent challenge, a topic explored in depth in discussions about AI’s impact on the evolving U.S. job market.
The Role of Public-Private Partnerships
Government incentives and private sector innovation are increasingly intertwined. Public-private partnerships are not just a buzzword; they are becoming a necessity for large-scale industrial revitalization. Consider the CHIPS Act, which has already catalyzed billions in private investment for semiconductor manufacturing within the U.S. — an exceptional level of government-backed industrial policy. These partnerships aim to de-risk substantial capital outlays for companies, particularly in nascent or strategically critical sectors. For example, a consortium involving General Electric and the Department of Energy recently announced a $150 million joint venture to accelerate advanced materials research for renewable energy components. Such collaborations provide shared infrastructure, foster research and development, and ensure a stable regulatory environment, all of which are magnetic for further private investment. It’s like two separate engines, running on different fuels, but synchronized to power the same massive ship.
Navigating Global Trade Dynamics
Global trade dynamics are a constant, unpredictable current that manufacturing investments must navigate. The push for reshoring and nearshoring, while driven by national security and supply chain resilience, is also a direct response to geopolitical tensions and shifting trade policies. Companies are strategically diversifying their manufacturing footprints to mitigate risks, prioritizing stability over the lowest possible cost.
Impact of International Agreements on Domestic Investment
International agreements, or the lack thereof, profoundly influence domestic investment decisions. Take, for instance, the ongoing shifts in trade relationships with key economic blocs. New tariffs or revised trade pacts can either incentivize or deter investment in American facilities. Dr. Emily Carter, an economist at the Peterson Institute for International Economics, highlights that “predictable, stable trade policies are significant for long-term manufacturing investment, far outweighing short-term cost advantages.” The uncertainty surrounding certain international trade negotiations can make investors hesitant, leading to capital flight or delayed projects. This delicate balance between global integration and domestic protectionism creates a challenging environment, one that often feels like unpacking new federal regulations every other week. To capitalize on these trends, businesses should consider a rigorous checklist:
- Assess AI and Automation Readiness: Evaluate current operational capabilities and identify areas ripe for AI-driven optimization and robotics integration.
- Explore Public Funding Avenues: Research federal and state grants, tax incentives, and partnership opportunities relevant to your sector.
- Diversify Supply Chains: Strategically review and expand supplier networks, incorporating regional and domestic options to enhance resilience.
- Invest in Workforce Reskilling: Develop internal training programs or partner with educational institutions to prepare employees for advanced manufacturing roles.
- Monitor Geopolitical Shifts: Stay informed on trade policy changes, international agreements, and geopolitical events that could impact supply chains and market access.
The future isn’t just about making things; it’s about making things smarter, faster, and with an eye towards global volatility.
The Enduring Resilience of American Industry
As we look ahead, the narrative of American manufacturing is not one of mere recovery, but of strategic reinvention. The critical question isn’t whether investment will continue, but how effectively the nation can harness these trends to build an industrial base that is not only strong but also adaptable to future shocks. The path forward demands continuous innovation in technology, a proactive approach to workforce development, and a policy environment that fosters long-term growth. Can the United States cement its position as a global manufacturing leader by focusing on resilience and high-value production, or will unforeseen global shifts once again challenge its industrial ambitions?
Frequently Asked Questions About American Manufacturing Investment
What are the primary government incentives for manufacturing investment in the US?
The US government offers significant incentives, primarily through legislation like the Inflation Reduction Act (IRA) and the CHIPS and Science Act. These acts provide substantial tax credits, grants, and subsidies for domestic production in critical sectors such as clean energy, semiconductors, and electric vehicle components, aiming to reduce reliance on foreign supply chains and stimulate job growth.
Which manufacturing sectors are currently experiencing the most growth in the US?
Key sectors experiencing significant growth include semiconductors, driven by the CHIPS Act; electric vehicle (EV) batteries and components, fueled by the accelerating EV revolution; and renewable energy manufacturing, particularly solar panels and wind turbine components, boosted by IRA incentives. Biotechnology production is also seeing substantial investment.
How do supply chain issues influence American manufacturing investment decisions?
Recent global crises highlighted the fragility of extended supply chains, prompting companies to prioritize resilience over just cost efficiency. This has led to widespread supply chain de-risking, nearshoring, and reshoring strategies, where production is brought closer to home to mitigate risks from geopolitical instability or logistical bottlenecks, directly influencing investment decisions.
What role does automation play in the future of US manufacturing?
Automation is important for the future of US manufacturing, boosting efficiency, consistency, and worker safety. Technologies like AI, robotics, and 3D printing are streamlining production lines, predicting maintenance needs, and freeing human workers for higher-value tasks. While requiring significant upfront investment and specialized skills, automation is seen as primary for competitive growth.
Are there significant regional differences in manufacturing investment across the United States?
Yes, there are notable regional differences, often influenced by specific state incentives, existing industrial ecosystems, and proximity to resources or markets. For example, states like Ohio, Arizona, and Texas are seeing massive semiconductor investments, while the Midwest and Southeast are becoming hubs for EV battery and component manufacturing, and states with strong renewable energy resources are attracting green tech production.