Student Loan Repayment Strategies for 2026: Navigating New Federal Programs and Saving 8% on Your Monthly Payments
The landscape of student loan repayment is constantly evolving, and 2026 promises to bring both new challenges and significant opportunities for borrowers. With federal programs undergoing revisions and the economic climate shifting, understanding the latest strategies is paramount to managing your debt effectively. This comprehensive guide will delve into the critical aspects of student loan repayment 2026, helping you navigate the complexities, leverage new federal programs, and potentially save a substantial 8% on your monthly payments. Whether you’re a recent graduate or have been repaying for years, the insights here will equip you with the knowledge to optimize your financial future.
Student loan debt continues to be a major concern for millions of Americans. As of late 2023, federal student loan debt alone surpassed $1.6 trillion, affecting over 43 million borrowers. The average student loan debt per borrower stands at approximately $37,000. These figures underscore the importance of having a robust and informed repayment strategy. The year 2026 is particularly significant as it will be well into the implementation phase of recent federal policy changes, offering a clearer picture of their long-term impact and how borrowers can best benefit.
Our goal is to demystify the options available, provide actionable advice, and empower you to make informed decisions that lead to significant savings and a clearer path to financial freedom. We’ll explore everything from understanding your current loan status to evaluating income-driven repayment plans, refinancing opportunities, and the often-overlooked benefits of strategic budgeting.
Understanding Your Student Loans: A Prerequisite for Success in 2026
Before diving into specific strategies for student loan repayment 2026, it’s crucial to have a clear understanding of your current loan portfolio. Many borrowers only have a vague idea of their loan types, interest rates, and servicers. This lack of clarity can hinder effective repayment planning. Start by gathering all necessary information:
- Federal vs. Private Loans: This is the most fundamental distinction. Federal loans offer protections and repayment options not available with private loans. Knowing which you have will dictate your available strategies.
- Loan Types: Within federal loans, distinguish between Stafford (Direct Subsidized/Unsubsidized), PLUS, and Perkins loans, as their terms and eligibility for certain programs can differ.
- Interest Rates: High-interest loans should often be prioritized in repayment strategies.
- Loan Servicers: Knowing who services your loans (e.g., Nelnet, MOHELA, Aidvantage) is essential for accessing your account, making payments, and discussing repayment options.
- Current Balance and Accrued Interest: Get an up-to-date total of your principal and any capitalized or uncapitalized interest.
You can find information about your federal student loans by logging into your account on StudentAid.gov. For private loans, you’ll need to contact your individual lenders or check your credit report.
The SAVE Plan: A Game Changer for Federal Student Loan Repayment in 2026
One of the most significant developments impacting student loan repayment 2026 is the full implementation of the Saving on a Valuable Education (SAVE) Plan. This new income-driven repayment (IDR) plan replaced the REPAYE Plan and offers substantial benefits, particularly for low- and middle-income borrowers. Understanding its mechanics is key to optimizing your payments.
Key Features of the SAVE Plan:
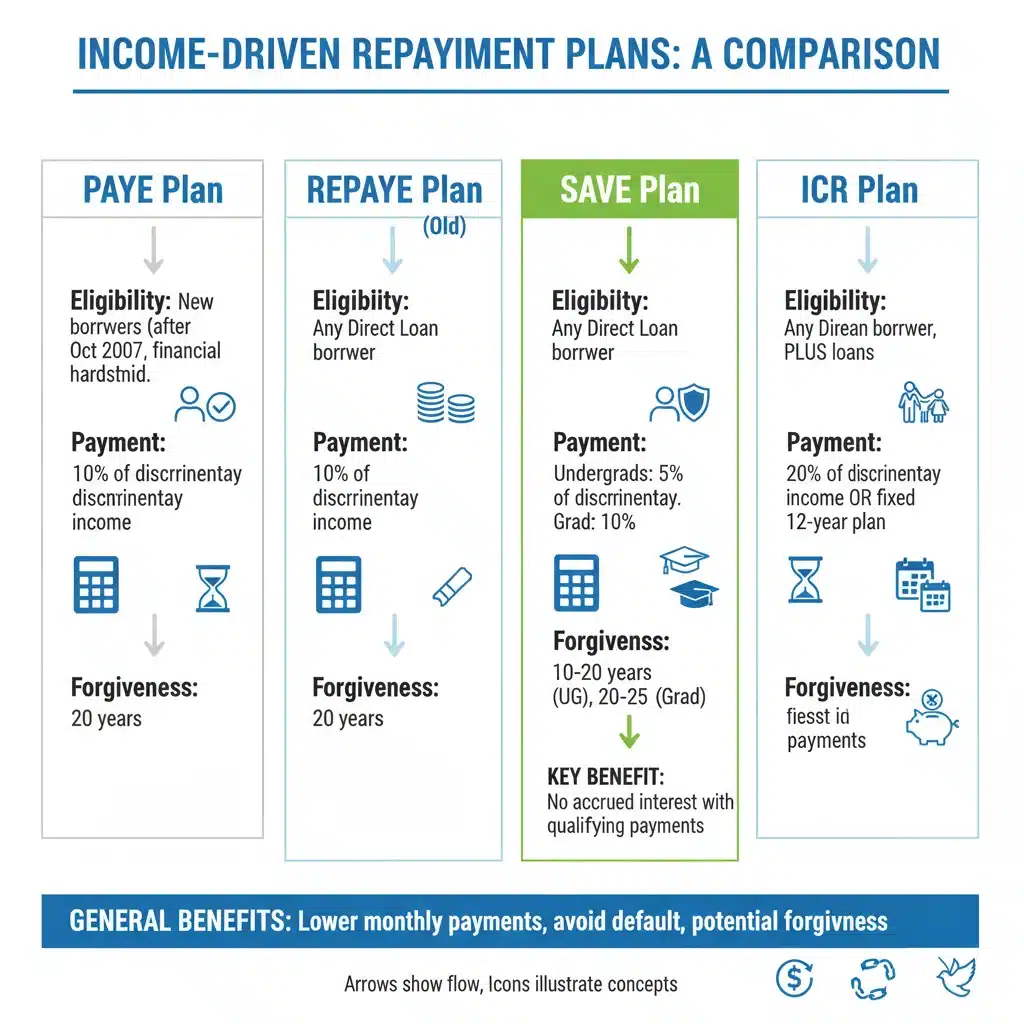
- Lower Monthly Payments: The SAVE Plan calculates your monthly payment based on a smaller percentage of your discretionary income compared to previous IDR plans. For undergraduate loans, payments are capped at 5% of your discretionary income, down from 10%. For graduate loans, it remains at 10%, and for those with both, it’s a weighted average.
- Increased Income Exemption: Discretionary income is now defined as the amount exceeding 225% of the federal poverty line, up from 150%. This means more of your income is protected, leading to lower monthly payments. For a single borrower, this could mean an additional $1,000 or more per month in protected income, significantly reducing their calculated payment.
- Interest Subsidy: This is a massive benefit. If your calculated monthly payment doesn’t cover the accrued interest, the government covers the remaining interest. This prevents your loan balance from growing due to unpaid interest, a common issue with other IDR plans. This feature alone can save borrowers thousands of dollars over the life of their loan and prevent the demoralizing experience of seeing their balance grow despite making payments.
- Shorter Path to Forgiveness: For borrowers with original principal balances of $12,000 or less, loan forgiveness can occur after just 10 years of payments, down from 20 or 25 years. This is a significant incentive for borrowers with smaller loan amounts. For every additional $1,000 borrowed above $12,000, an additional year is added to the repayment term before forgiveness, up to the standard 20 or 25 years.
- Spousal Income Exclusion: If you are married and file separately, your spouse’s income is not included in the calculation of your discretionary income, which can further lower your payments.
Example of SAVE Plan Savings: Consider a borrower with $30,000 in undergraduate loans, earning $40,000 annually. Under the old REPAYE plan, their discretionary income calculation might have led to a payment of around $150-$200. Under SAVE, with the 225% poverty line exemption and 5% discretionary income cap, their payment could drop to $0-$50, and any unpaid interest would be subsidized. This represents a substantial monthly saving and prevents balance growth.
Action Step: If you have federal student loans, apply for the SAVE Plan on StudentAid.gov to see if it lowers your payments. Even if you’re on another IDR plan, you might be automatically transitioned or benefit from switching.
Other Federal Repayment Options and Forgiveness Programs in 2026
While the SAVE Plan is a major focus for student loan repayment 2026, it’s not the only federal option. Other IDR plans and forgiveness programs remain relevant:
Other Income-Driven Repayment (IDR) Plans:
- Pay As You Earn (PAYE): Payments are 10% of discretionary income, capped at the standard 10-year payment amount. Forgiveness after 20 years.
- Income-Based Repayment (IBR): Payments are 10% or 15% of discretionary income (depending on when you borrowed), capped at the standard 10-year payment amount. Forgiveness after 20 or 25 years.
- Income-Contingent Repayment (ICR): Payments are either 20% of discretionary income or what you’d pay on a fixed 12-year plan, whichever is less. Forgiveness after 25 years.
It’s crucial to compare these plans, especially if you have older loans that might not qualify for SAVE or if your financial situation makes another plan more advantageous. The Loan Simulator on StudentAid.gov is an invaluable tool for this comparison.
Public Service Loan Forgiveness (PSLF):
PSLF remains a powerful program for borrowers working in eligible public service jobs. After making 120 qualifying monthly payments (10 years) under a qualifying repayment plan (typically an IDR plan, including SAVE) while working full-time for a government or non-profit organization, your remaining federal Direct Loan balance can be forgiven tax-free. The program has seen significant improvements in recent years, making it more accessible.
Action Step: If you work in public service, ensure you are on a qualifying IDR plan and submit the PSLF Form annually to track your progress and confirm your employment eligibility. Don’t wait until you think you’re close to forgiveness to submit this form!
Teacher Loan Forgiveness and Other Forgiveness Programs:
Other specific forgiveness programs exist for teachers, nurses, and other professions. Research these options on StudentAid.gov to see if you qualify. While less comprehensive than PSLF, they can still offer significant relief.
Strategic Approaches to Saving 8% on Your Monthly Payments in 2026
Achieving an 8% reduction in your monthly student loan payments is an ambitious yet attainable goal through a combination of leveraging federal programs and adopting smart financial habits. Here’s how to approach it:
1. Maximize Federal Program Benefits (Potential 3-5% Savings)
- Enroll in the SAVE Plan: As discussed, this is your primary tool for federal loan savings. The interest subsidy and lower discretionary income percentage can dramatically reduce your out-of-pocket payments, potentially by 3-5% or more compared to standard or older IDR plans, especially if your income is modest relative to your debt.
- Recertify Income Annually (or Sooner): Your IDR payment is based on your income and family size. If your income decreases or your family size increases, recertify immediately to lower your payments. Do not wait for your annual recertification date.
- Explore PSLF: If you’re eligible, PSLF effectively reduces your total repayment obligation to 10 years of payments, which can translate to massive long-term savings and a lower effective monthly cost over the life of your debt.
2. Smart Budgeting and Expense Reduction (Potential 2-3% Savings)
Saving money on your student loans isn’t just about the loan itself; it’s also about freeing up cash flow. A well-structured budget can help you find extra funds to either make larger payments (if you’re trying to pay off debt faster) or simply reduce financial stress by creating a buffer.
- Track Your Spending: Use budgeting apps or spreadsheets to categorize every dollar you spend. Many people are surprised by how much they spend on non-essentials.
- Identify and Cut Unnecessary Expenses: Look for subscriptions you don’t use, reduce dining out, or find cheaper alternatives for daily necessities. Even small cuts add up.
- The "Latte Factor" Still Applies: While a single coffee won’t break the bank, daily small purchases can accumulate. Be mindful of these habits.
- Negotiate Bills: Call your internet, cable, or insurance providers to see if you can get a better rate.
Example: If your monthly student loan payment is $400, an 8% saving would be $32. If your current budget has $150 allocated to dining out and $50 to unused subscriptions, cutting those back could easily free up the $32 (and more) to either lower your payment through an IDR plan or put towards other financial goals.
3. Consider Refinancing Private Loans (Potential 1-2% Savings)
For private student loans, refinancing can be a powerful tool to reduce your interest rate and monthly payment. Federal loans generally should NOT be refinanced into private loans, as you lose crucial federal protections like IDR plans and forgiveness options.
- Shop Around: Compare offers from multiple private lenders. Rates can vary significantly based on your credit score, income, and debt-to-income ratio.
- Improve Your Credit Score: A higher credit score will qualify you for better interest rates. Pay bills on time, reduce credit card debt, and avoid opening new lines of credit before applying.
- Shorten or Extend Loan Term: Refinancing allows you to choose a new loan term. A shorter term means higher monthly payments but less interest paid overall. A longer term means lower monthly payments but more interest paid over time. Choose the option that aligns with your financial goals.
Caution: Refinancing federal loans into private loans means forfeiting access to federal benefits, including IDR plans, forbearance, deferment, and forgiveness programs like PSLF. Only consider this for private loans, or if you are absolutely certain you will not need federal protections and can secure a significantly lower interest rate.
Proactive Steps for All Borrowers in 2026
Beyond specific programs and budgeting, certain proactive steps can ensure you’re always in the best position for student loan repayment 2026:
Stay Informed:
- Monitor StudentAid.gov: This is the official source for federal student loan information. Regularly check for updates on policies, programs, and repayment options.
- Subscribe to Servicer Communications: Ensure your loan servicer has your current contact information and pay attention to their emails and mail.
- Follow Financial News: Policy changes can happen quickly. Staying abreast of financial news sources that cover student loans can give you an early heads-up on potential shifts.
Build an Emergency Fund:
Having 3-6 months of living expenses saved can be a lifesaver if you face unexpected job loss or medical emergencies. This prevents you from missing student loan payments and potentially defaulting, which can severely damage your credit.
Consider Extra Payments (If Feasible):
If you’re on a standard repayment plan and have extra income, making additional principal payments can significantly reduce the total interest paid and shorten your repayment term. Ensure your servicer applies extra payments directly to the principal of your highest-interest loan.
Automate Payments:
Setting up automatic payments can often qualify you for a small interest rate reduction (typically 0.25%) from your servicer, and it helps ensure you never miss a payment, protecting your credit score.
Seek Professional Advice:
If your situation is complex, consider consulting with a non-profit credit counselor or a financial advisor specializing in student loan debt. They can provide personalized guidance and help you navigate the best path forward.
Potential Challenges and How to Address Them in 2026
While 2026 offers many opportunities, borrowers may still face challenges:
- Economic Instability: Fluctuations in the job market or personal income can impact your ability to make payments. The flexibility of IDR plans like SAVE is crucial here.
- Servicer Changes: The student loan servicing landscape can change. If your servicer changes, ensure you update your contact information and understand the transition process.
- Scams: Be wary of companies promising quick fixes or guaranteed forgiveness for a fee. Most services they offer can be done for free through StudentAid.gov.
- Information Overload: The sheer volume of information can be overwhelming. Focus on official sources and use tools like the Loan Simulator to simplify your options.
By being prepared for these challenges, you can mitigate their impact on your student loan repayment 2026 journey.
Long-Term Planning: Beyond 2026
Effective student loan management isn’t just about the immediate future; it’s about setting yourself up for long-term financial health. As you implement your student loan repayment 2026 strategies, consider these long-term goals:
- Debt-to-Income Ratio: Keep an eye on your debt-to-income ratio, especially if you plan to buy a home or take out other significant loans. Lowering your student loan payments or principal can improve this ratio.
- Retirement Savings: While student loans are a priority, don’t neglect retirement savings. If your employer offers a 401(k) match, contribute at least enough to get the full match – it’s free money.
- Investment Opportunities: Once your student loans are manageable, explore investment opportunities to grow your wealth.
- Financial Literacy: Continuously educate yourself on personal finance. The more you know, the better equipped you’ll be to adapt to future changes.
Conclusion: Empowering Your Student Loan Journey in 2026
Navigating student loan repayment in 2026 requires diligence, awareness, and strategic planning. By thoroughly understanding your loan types, leveraging powerful federal programs like the SAVE Plan, adopting smart budgeting techniques, and considering refinancing for private loans, you can make significant strides in reducing your financial burden. The goal of saving 8% on your monthly payments is well within reach through a combination of these approaches.
Remember, the key is to be proactive. Don’t wait for problems to arise. Regularly review your loan status, stay informed about policy changes, and utilize the resources available to you. With the right strategies in place, 2026 can be the year you take significant control over your student loan debt, paving the way for greater financial stability and peace of mind.
Take the first step today: log into StudentAid.gov, assess your current situation, and explore how the SAVE Plan and other options can transform your student loan repayment 2026 strategy. Your future self will thank you.